A homeowner called me once convinced her lender owned her house. It didn’t. She did. One misunderstanding cost her two years of worry she never needed to carry, and it’s the single most common thing I correct when a family calls me about a reverse mortgage.
It happens every day, and the equity question usually has a better answer than families fear.
What Is a Reverse Mortgage and How Does Selling One Work?
Families walk in picturing a sale where the lender takes the house and everyone goes home empty-handed.
You keep the deed the whole time. A reverse mortgage is a lien against your property, same as any other mortgage, just running in the opposite direction. Instead of you paying the lender down each month, the lender advanced you money. Interest and the annual mortgage insurance premium add to it, growing the balance.
Most of these loans are federally insured through FHA and go by the name Home Equity Conversion Mortgage, or HECM. A payoff quote on a HECM isn’t like a payoff on a regular loan; the figure wraps in accrued interest, the MIP, and servicing fees on top of what the borrower drew. Depending on which month you close, the number moves, which explains it.
The mechanics of the sale itself? Nearly identical to any other closing. You list or sell directly, a buyer comes to the table, escrow orders the payoff, and the title company wires the lender its money before any of it reaches you.
Early last year I bought a house in Tacoma from an heir who’d taken a job transfer and had five weeks to be out of state. His mother’s reverse mortgage was the thing he dreaded most, and it turned out to be the easiest part of the file.
When Do You Have to Sell a House with a Reverse Mortgage?
For years I told people the loan came due the day the borrower passed away, full stop.
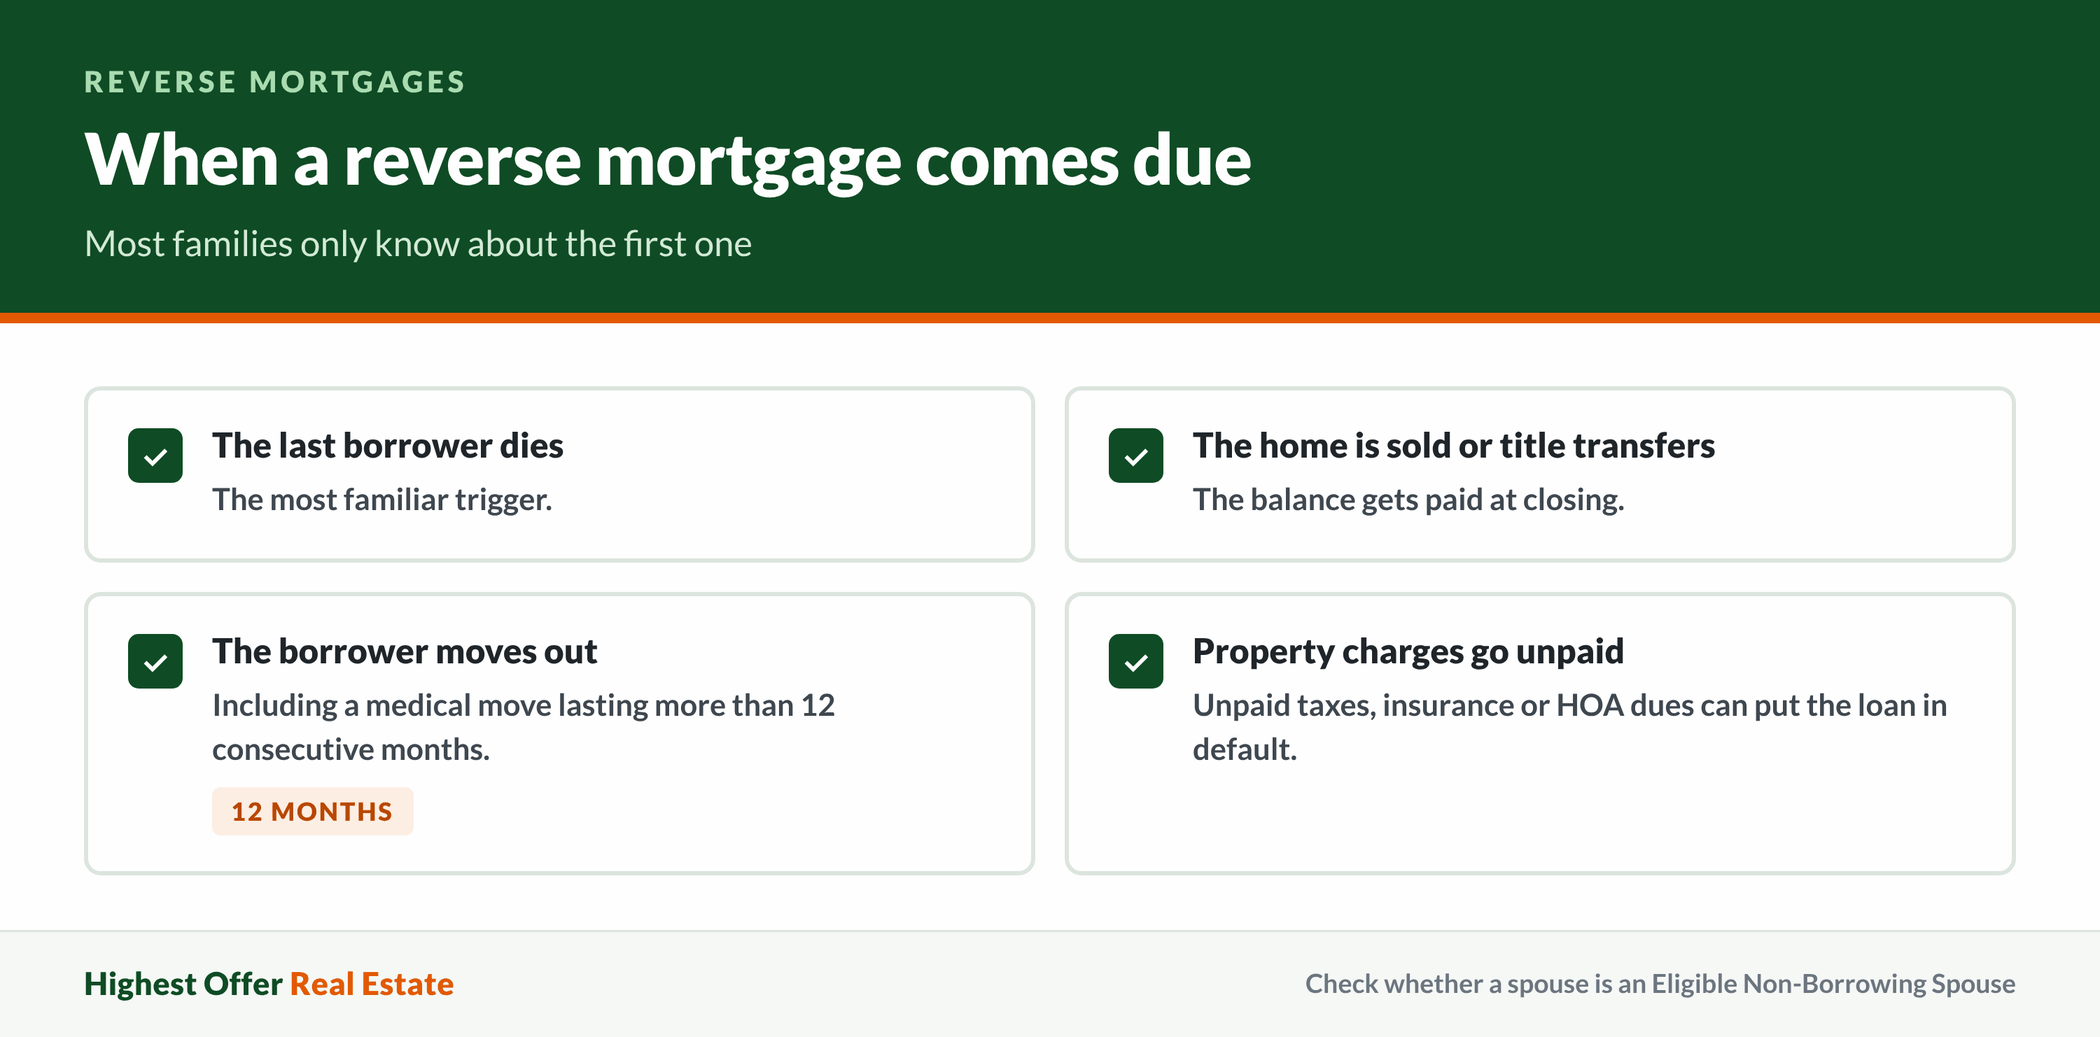
Death of the last borrower is one trigger. Selling or transferring title is another. Permanent move-out is the one people miss entirely, and it’s got a measurable line attached to it. A HECM comes due if you die or move out of the home, including a medical move lasting more than 12 consecutive months, the Consumer Financial Protection Bureau explains. A long rehab stay can.
Don’t ignore property charges. Even with no monthly payment due, the borrower still owes property taxes, homeowners insurance, and any HOA dues, and letting those slide can put the loan into default. I’ve seen more reverse mortgage trouble start with an unpaid insurance bill than with anything else.
A spouse who wasn’t on the loan deserves real attention here. Your spouse may not be a co-borrower, even if married to you when the reverse mortgage was taken out. They may be able to stay in the home without paying off the balance after your death or a long health care facility stay, provided they qualify under HUD’s rules. Call the servicer and ask directly whether they’re on file as an Eligible Non-Borrowing Spouse before you assume anything.
So should you sell the moment the loan comes due? Not necessarily. Selling early, while the borrower’s alive and the balance is smaller, often preserves more equity than waiting does, because interest and the insurance premium keep getting added every single month you hold.
Can Someone Buy a Home That Has a Reverse Mortgage on It?
Yes, and the buyer almost never knows or cares.
It shows up, it gets paid at closing, it releases. Nobody’s buying “a reverse mortgage house.” They’re buying a house that happens to have one loan on it.
Things get interesting when a family member is buying the property. When an heir keeps the home or a relative buys it, the payoff is capped at 95% of the current appraised value rather than the full balance. The cap only applies in those situations, not to an arm’s-length buyer off the open market.
Cash works fine, and so do direct buyers, since the lien doesn’t discriminate.
What does trip up these transactions is timing. Payoff statements expire, servicers order appraisals on their own schedule, and a buyer with a 45-day loan commitment can run out of runway waiting on a lender’s payoff department to return a call. Sellers in this spot should ask any prospective buyer how fast they can close and whether they’ve handled a HECM payoff before.
Sellers have less cushion now than they used to. The National Association of Realtors put median time on market at 35 days in October 2026, up from 33 in September. Inventory stood at a 5.1-month supply. This means sellers hold less leverage than a year ago. Add the weeks between contract and closing and a listing started today may not fund for two months or more.
At Highest Offer Real Estate, we’ve closed plenty of these, and the single biggest favor a seller can do for themselves is request the payoff statement before the house ever hits the market.
What Steps Are Involved in Selling a Home with a Reverse Mortgage?
“Where do I even start?”
Start with the servicer, not the agent. Call the number on the statement, identify yourself (borrower, heir, executor, power of attorney), and request a written payoff quote with its expiration date. Ask what documentation they need from you to release information if you’re not the borrower.
Next comes a realistic value. Not a Zillow number, not what the neighbor got in 2022. A current appraisal or a solid comparative market analysis tells you whether you’re sitting on equity or staring at a shortfall, and in my experience that single answer determines everything you do afterward.
Then you choose your path. Listing with a real estate agent makes sense when the property shows well and you have time on your side.
Once you’re under contract, escrow takes over the heavy lifting. The title company orders an updated payoff, confirms the figure in writing, and disburses in order: reverse mortgage first, then liens, taxes, and closing costs, then whatever’s left to you.
Heirs lose weeks to documentation, and it’s usually what trips up closing. A death certificate, letters testamentary or a trustee certification, and a clear chain of title all need to exist before closing, and probate court schedules don’t bend for your contract date. Open that file the same week you call the servicer.
One pattern I keep seeing: families who wait to clean out the house until after they’ve accepted an offer. Do it in parallel.
How Do You Pay Off a Reverse Mortgage When the House Sells?
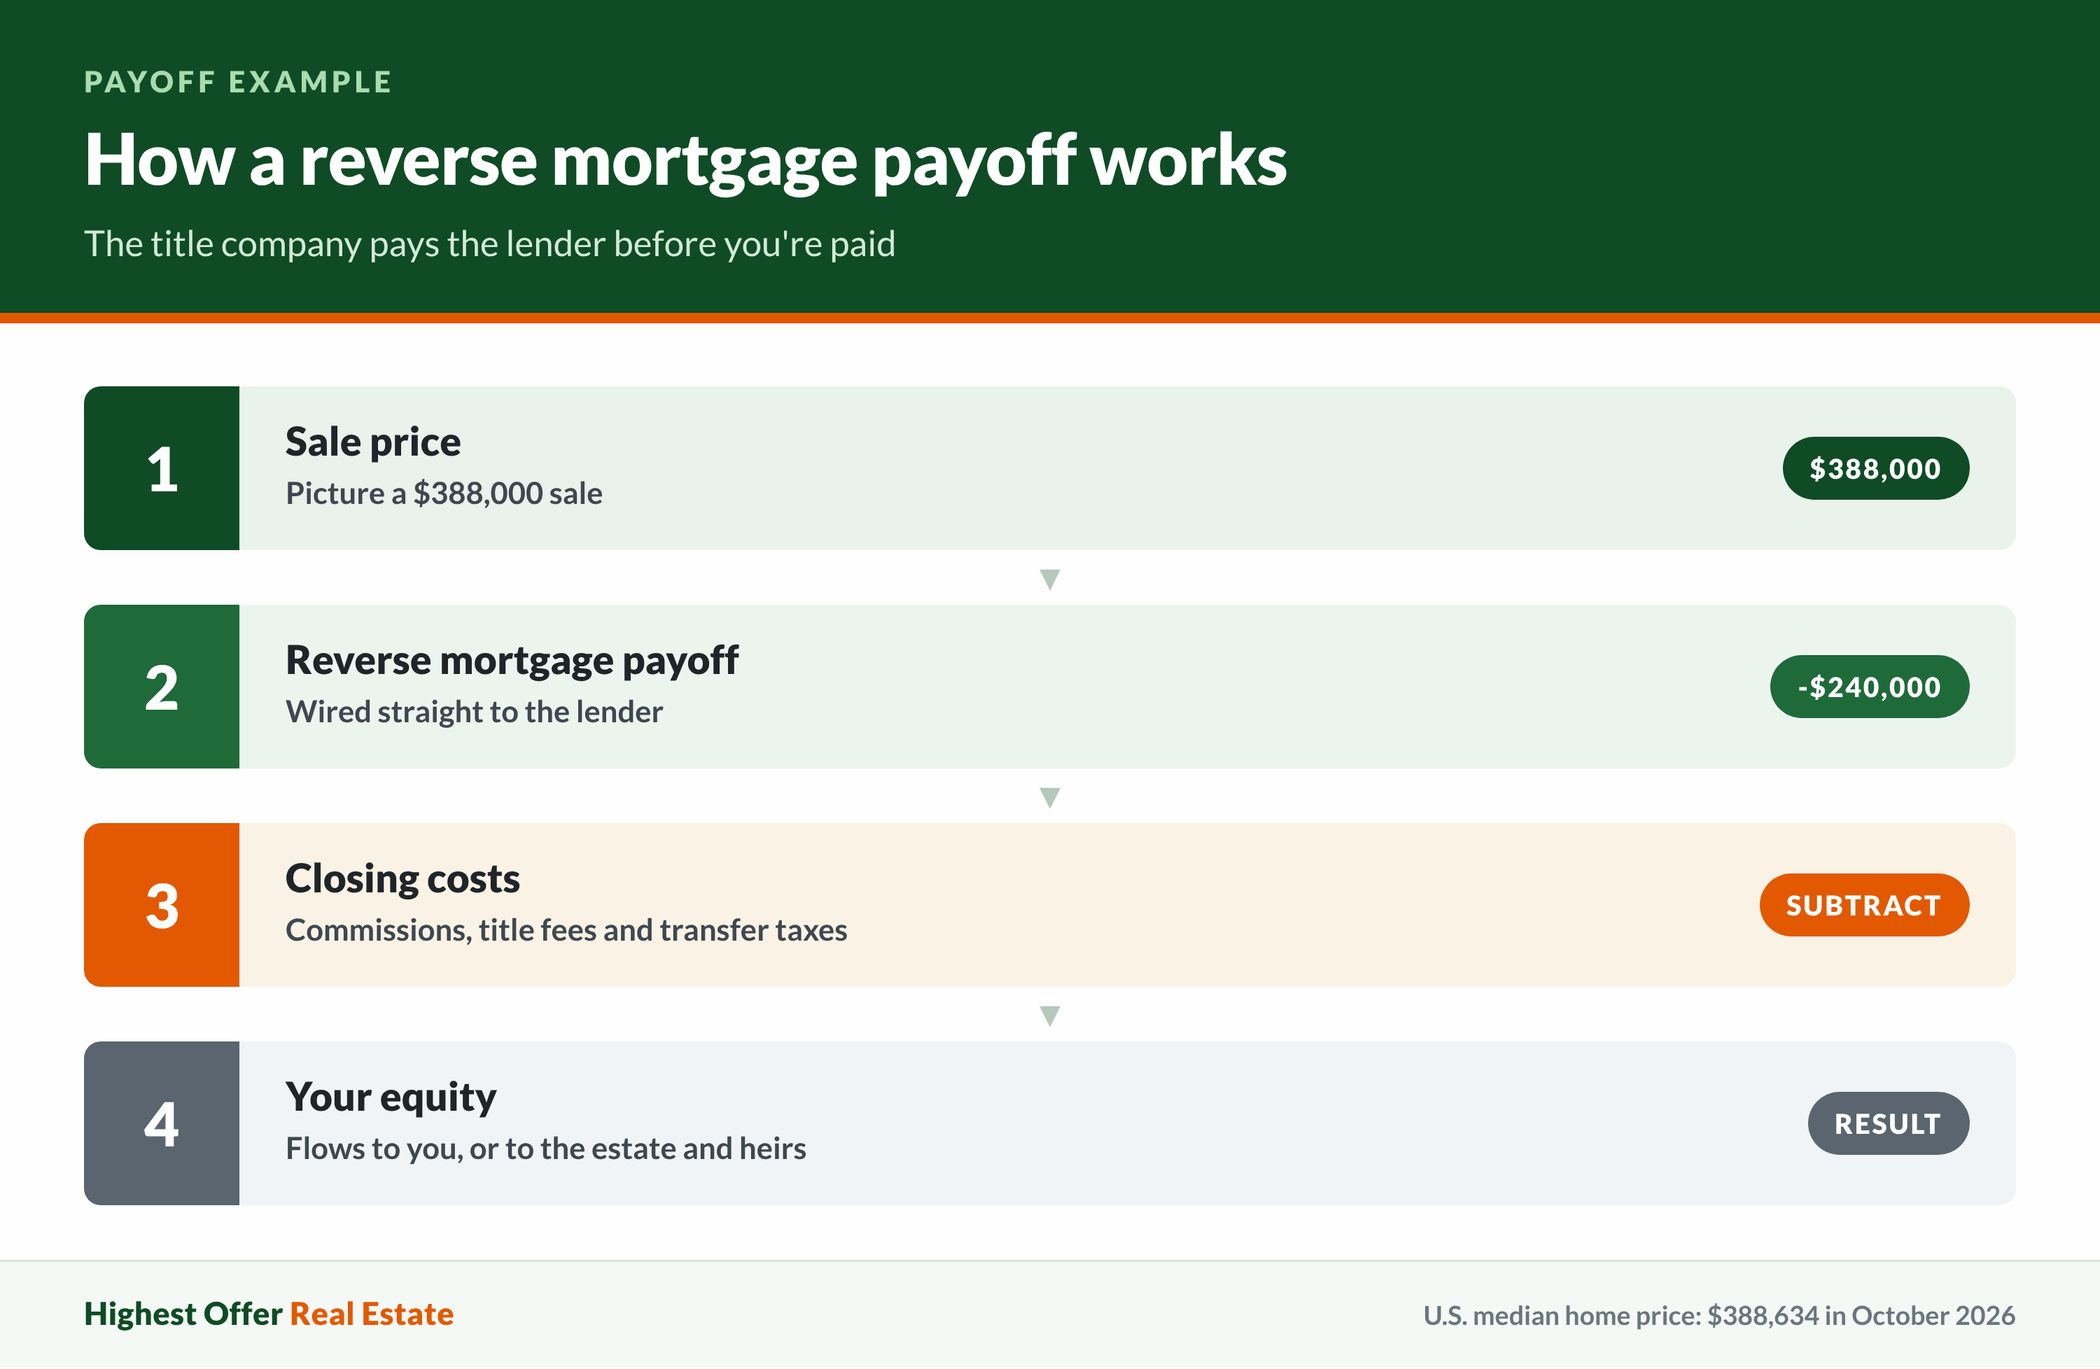
Picture a $388,000 sale against a $240,000 balance. A realistic frame right now, since U.S. home prices in October 2026 came in at a median of $388,634, down 0.35% from a year earlier. The title company wires the lender its $240,000, closing costs come off, and what’s left lands in your pocket.
The title company pays the reverse mortgage balance directly out of the proceeds before any money gets distributed. That’s the whole mechanism, and it’s why a reverse mortgage payoff feels anticlimactic once you’re sitting at the closing table.
People give the payoff quote’s timing less credit than it deserves. Interest and the insurance premium keep being added month to month, so a quote pulled in March won’t match what’s owed in June. Escrow will pull a fresh one, but a stale number in your head leads to bad decisions about pricing.
When a sale falls short, things work a bit differently. When the sale price lands under the balance, the CFPB says heirs can satisfy the debt by selling for at least most of the appraised value. The rest is covered by the mortgage insurance the borrower paid into all along. That insurance fund exists precisely for this outcome.
Sellers sometimes ask whether they can negotiate the payoff down. When the home is worth more than the balance, that payoff isn’t negotiable below what’s owed.
Second liens complicate the order of operations. A home equity line, a contractor’s lien, or back property taxes all have to clear before the seller sees a dollar, and a title search catches those early enough to solve them.
What Happens to the Money After a Reverse Mortgage Home Sells?
Sit down with me for a minute, because this is the part where people exhale.
The equity is yours. Whatever remains after the HECM is satisfied flows to the estate and then to the heirs. A reverse mortgage doesn’t convert your house into the bank’s asset; it just puts a debt in line ahead of you.
What lands in your hands depends on three things you partly control: the sale price, how long the loan ran, and your transaction costs. Commissions, title fees, transfer taxes, and any repair credits, they all come off before the net hits your account.
Taxes deserve a conversation with a CPA, not a blog. Proceeds from a home sale may qualify for the federal capital gains exclusion if the property was your principal residence, and heirs typically get a stepped-up basis, which completely changes the math. State rules vary, and California in particular has its own property tax wrinkles for inherited property that a local tax professional should walk you through.
Does a shrinking market change what you’ll net? It does. Redfin reported sale prices fell nationally in October 2026 even as they climbed in more than half of the 50 largest metros, with San Francisco up 16.8% year over year. Where your house sits on that map determines whether waiting helps or hurts.
Will Heirs Owe Money If the Reverse Mortgage Balance Is Too High?
And that leads straight to the question families lose sleep over.
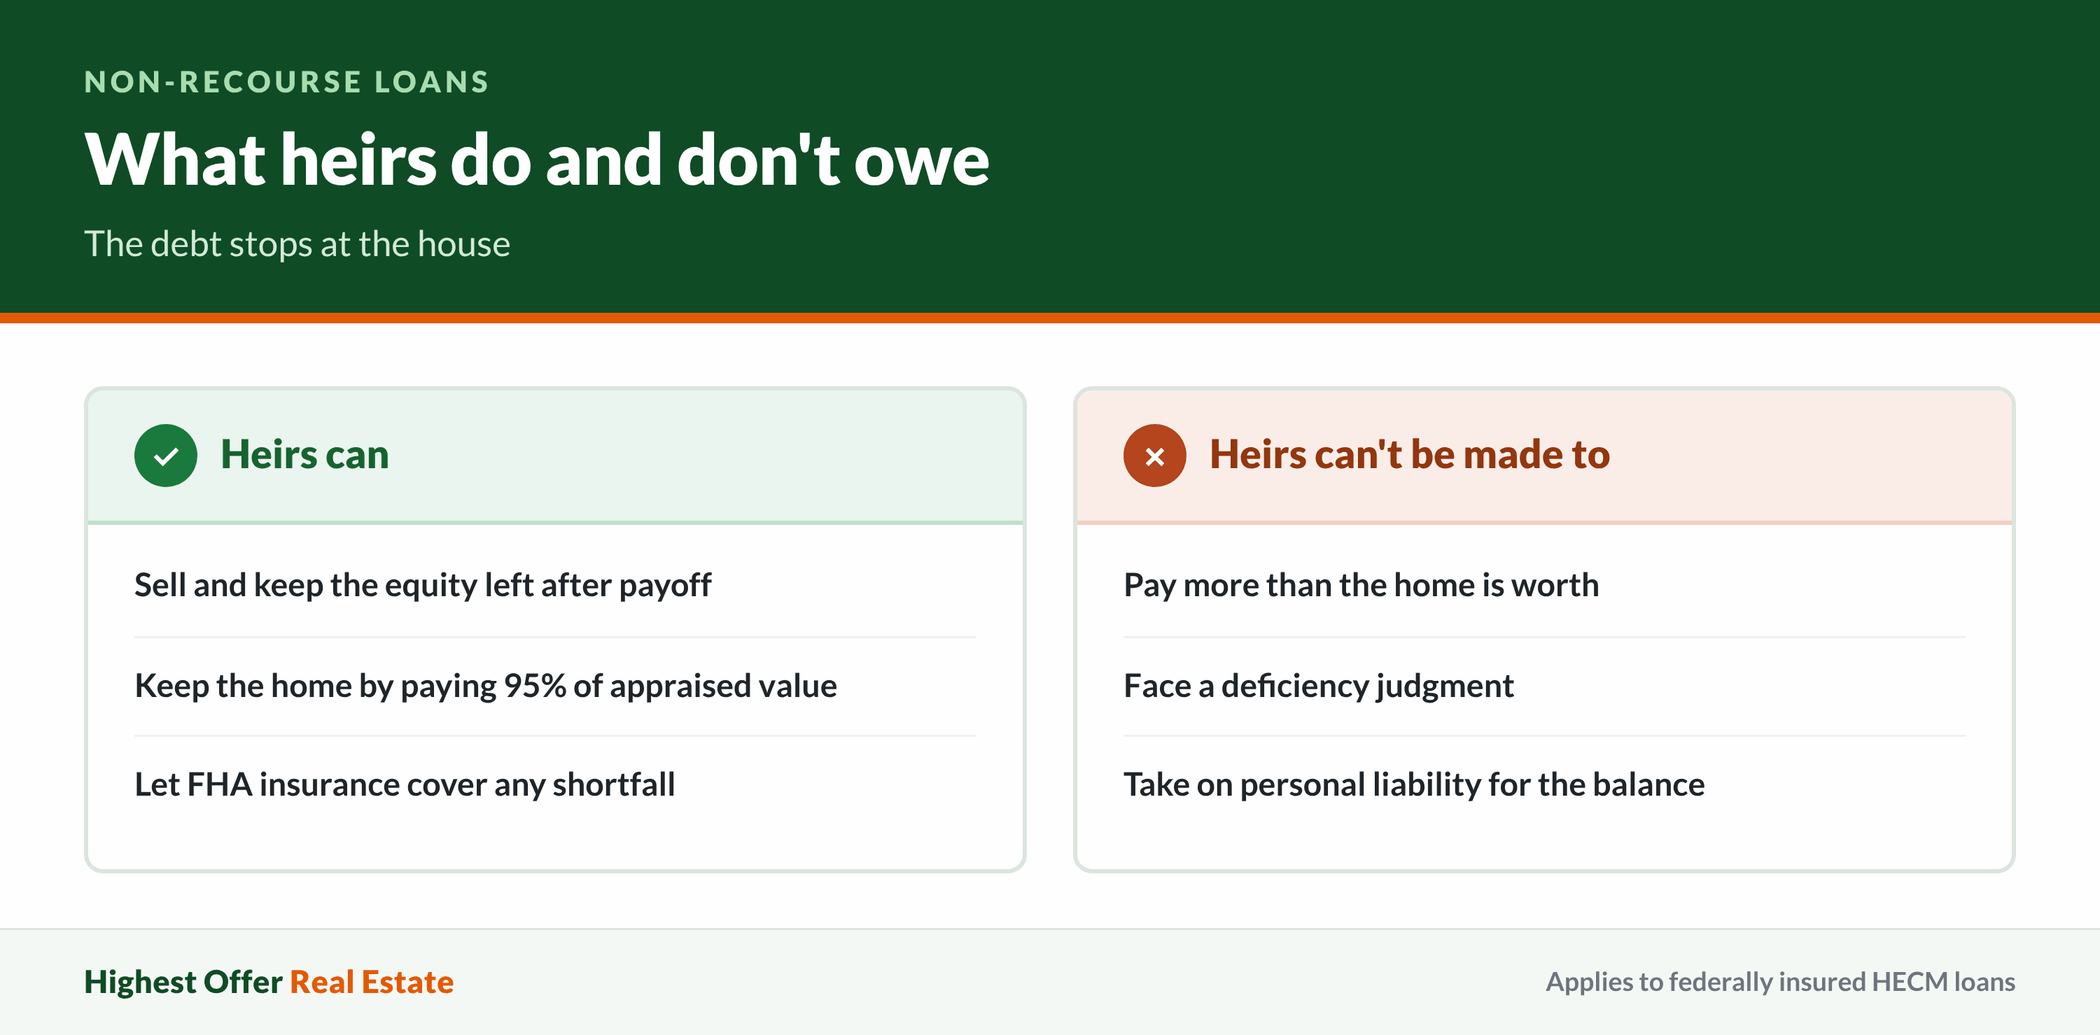
No. The debt stops at the house. A federally insured reverse mortgage is non-recourse. Neither the estate nor the heirs can be forced to pay more than the home is worth. When the balance has outgrown the property value, the FHA insurance fund absorbs the gap. There’s no bill coming to your mailbox after the sale.
HUD’s rules specifically bar the lender from pursuing a deficiency judgment on a HECM. No personal liability. That protection is bought and paid for by the mortgage insurance premiums the borrower carried for the life of the loan.
The other half of this protection is widely misread. Heirs satisfy the full debt by paying nearly all of the home’s current FHA-appraised market value, regardless of how far the loan balance has climbed past it.
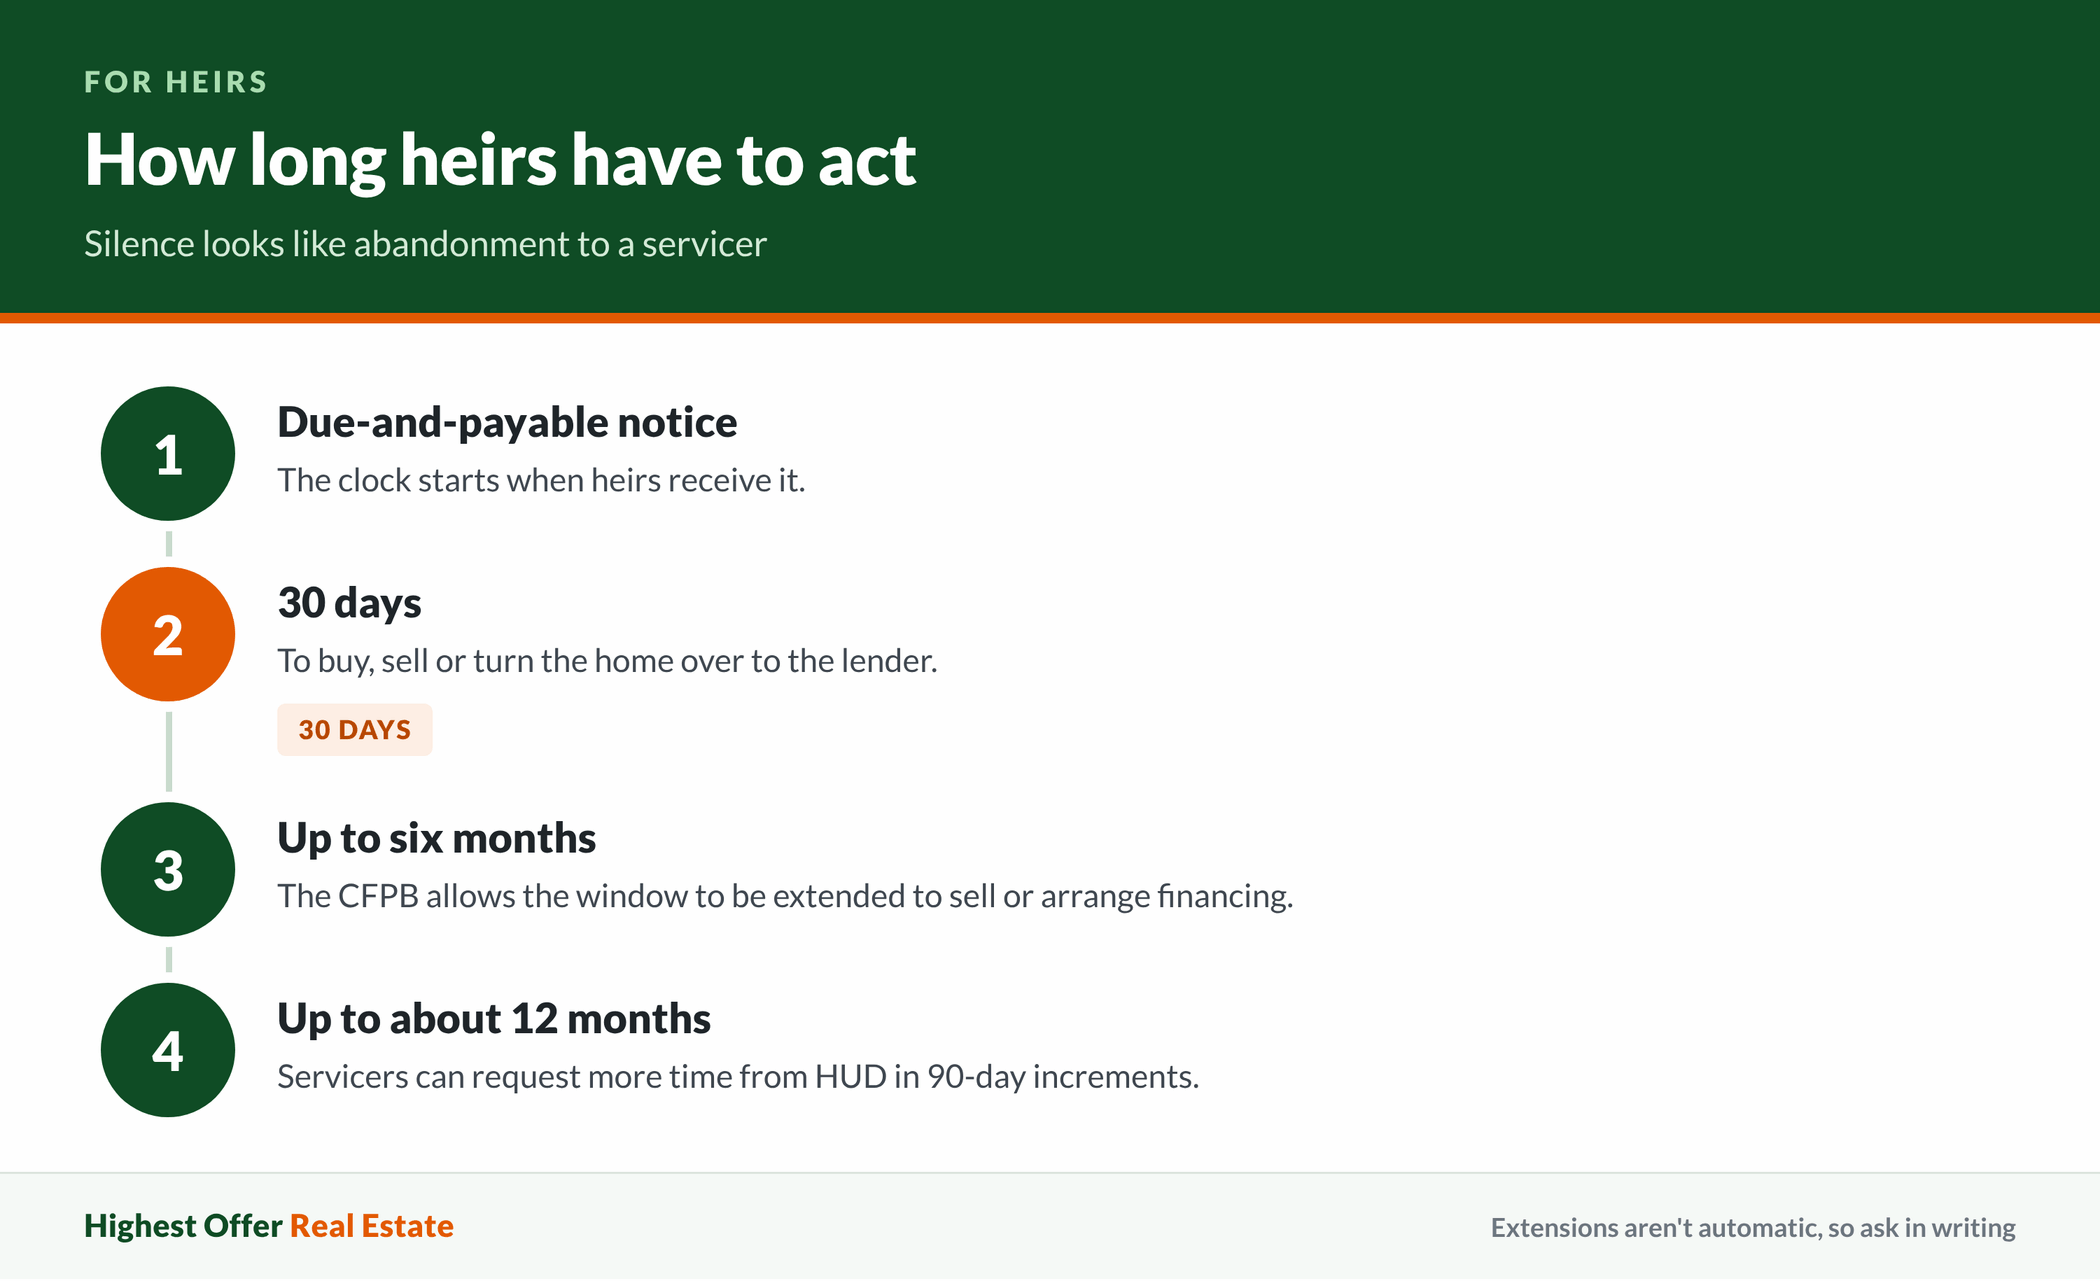
Timelines are where heirs get hurt, not liability. Heirs have 30 days once they receive the due-and-payable notice to buy, sell, or turn the home over to the lender. The CFPB allows that window to be extended up to six months to sell or arrange financing. Beyond that, servicers can generally request more time from HUD in 90-day increments, up to roughly 12 months in total, when the family is actively working a listing or a loan application.
Extensions aren’t automatic, though. Silence looks like abandonment to a servicer, and abandonment leads to foreclosure.
How Do You Find the Right Agent to Sell a Reverse Mortgage Home?
A family in Puyallup listed with a neighborhood agent who’d never seen a HECM payoff and lost 70 days to confusion over a servicer’s appraisal. They switched agents, closed in six weeks, and walked with real money.
Ask candidates one question: how many reverse mortgage closings have you handled? You’re not looking for the top producer in your zip code; you’re looking for someone who knows which department at the servicer returns calls.
Days on market swing hard by region right now. In Fort Lauderdale, the typical home went under contract in 90 days this October, 18 days faster than a year earlier. An agent who can tell you where your neighborhood sits against that kind of spread is an agent worth hiring, and a good one will also tell you when listing is the wrong move. Properties with deferred maintenance, cluttered estates, or a tight servicer deadline frequently net more through a direct sale than through a listing that sits, drops price twice, and then sells with repair credits anyway.
Interview at least two. Ask each to show you a net sheet, not a list price, because the list price isn’t what you keep.
A landlord in Lakewood called me after a contractor priced out her late father’s kitchen. The estimate came in higher than the kitchen would add to the house, with a cracked slab under the back corner nobody had mentioned for a decade. She’d owned rentals for twenty years and still almost spent the money out of habit; she sold it as-is instead and kept the difference.
If you’d rather skip the repair question entirely, a direct buyer like Highest Offer Real Estate can price the house in its current condition and work around a servicer’s deadline rather than against it.
Frequently Asked Questions
Can a Reverse Mortgage Be Foreclosed On?
Yes, though it usually takes a while and it’s almost always preventable. Foreclosure follows a default: unpaid property taxes or homeowners insurance, failure to maintain the property, or heirs who let the resolution window close without responding to the servicer. Staying in contact with your servicer and answering every notice in writing is the single most effective thing you can do. Servicers would rather see a payoff or a sale than take a property back.
Does Rocket Mortgage Offer Reverse Mortgages?
Lender participation in the HECM program changes over time, so check directly with any lender before counting on them. A better starting point is HUD’s list of FHA-approved lenders, which tells you who’s currently authorized to originate these loans in your state. If you’re selling rather than borrowing, the originating lender matters far less than the servicer currently holding the file, and that name appears on your statement.
What Does the 95 Percent Rule Mean for Heirs?
It means heirs who want to keep an underwater property can satisfy the entire debt by paying a fraction just under the home’s current appraised value. FHA insurance covers whatever the lender doesn’t collect. The appraisal that sets that figure is ordered by the servicer through a HUD-approved appraiser, not by you. This option belongs to heirs and family purchasers, not to an outside buyer on the open market.
What Are the Real Downsides of a Reverse Mortgage?
The balance grows the entire time the loan is outstanding, and that growth comes out of whatever equity would otherwise pass to your family. Property charges remain your responsibility, and falling behind on them can put the loan into default even though no monthly payment is due. Closing costs and the ongoing insurance premium are real money too. For a homeowner who plans to stay put for decades, the tradeoff can work; for someone likely to move within a few years, it rarely does.
Should I Sell Before or After the Loan Comes Due?
Selling while the borrower is still living and in the home often preserves more equity, because you control the timeline instead of racing a servicer’s clock. Waiting until after a death adds probate paperwork, a resolution deadline, and a balance that kept growing in the meantime. That said, a borrower who’s happy and settled shouldn’t sell just to beat an actuarial table; the right answer depends on whether anyone actually wants to live there.
If you’re sorting through a reverse mortgage on a house you own or inherited, we’re glad to walk through the numbers with you, including the option where you don’t sell to us at all. No pressure, no obligation, and no charge for a straight answer.
Reverse Mortgage Homes in Tacoma and Across Washington
We buy houses with reverse mortgages in Tacoma and Pierce County. The payoff works the same way it does anywhere, through escrow at closing.
Heirs and borrowers across Washington can ask us for an as-is offer that fits the servicer’s deadline.
Talk Through Your Reverse Mortgage Sale
Contact Highest Offer Real Estate and we’ll walk you through the payoff and what you could net.
You can also fill out the short form below. There’s no cost and no obligation.