Roughly two out of every three Washington homeowners are still paying off a loan on the place they live in. The norm is this, not some unfortunate exception. Yet almost every week I talk with someone in Tacoma or Everett who sounds embarrassed admitting they haven’t paid off their house. You don’t need a free-and-clear deed to sell. Selling with a mortgage is the standard transaction across Washington, and the mechanics are straightforward once sellers see how they work.
Is It Normal to Sell a Home with a Mortgage Still Owed?
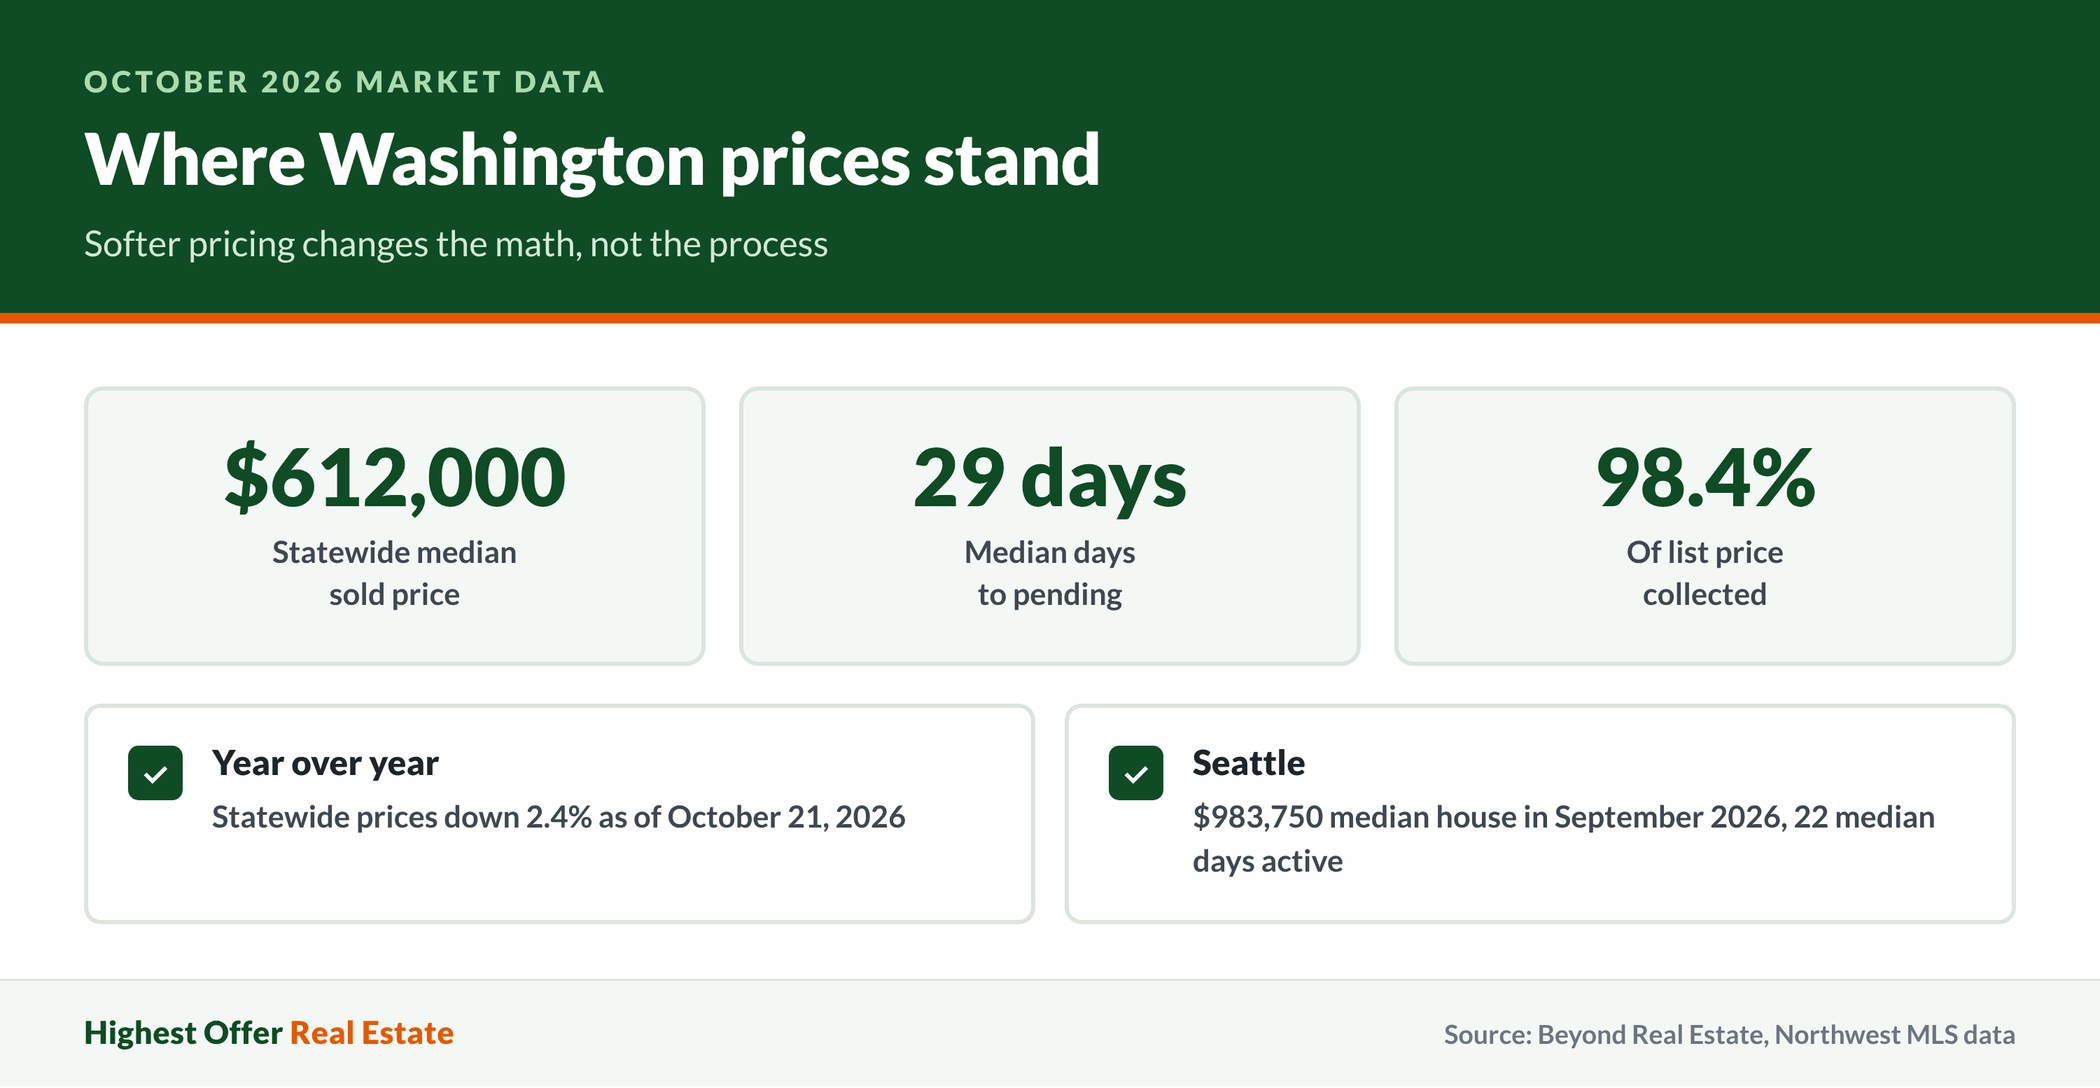
Washington’s statewide median sold price sat at $612,000 in early October 2026. Homes went pending in a median of 29 days, and sellers collected about 98.4 percent of list price. This is according to Beyond Real Estate data drawn from Northwest MLS listings. Almost every one of those closings involved a loan payoff, and title companies in Washington handle this hundreds of times a day without blinking.
Your lender doesn’t own your house. You do. The lender holds a lien, which is a legal claim against the property that gets satisfied out of the sale money before you see a dime. That’s the whole arrangement. Nothing about selling with a mortgage requires permission from your servicer.
A family in Lacey called me last year after one spouse got transferred to a position in Boise with a five week reporting date. They still owed about 70 percent of what the house was worth and had a camper trailer parked in the side yard, so they assumed they’d need to refinance before they could list. We closed in under four weeks and their loan was paid off at the table.
Washington’s market has softened a little, which changes the math but not the process. Statewide prices were down 2.4 percent year over year as of October 21, 2026, with sold homes averaging 98.5 percent of list price. Softer pricing means your payoff eats a slightly bigger share of your proceeds. It doesn’t block the sale.
Have you been putting off a move because you think the loan complicates everything? The instinct is understandable and usually wrong.
How Does Selling a House with a Mortgage Work in Washington
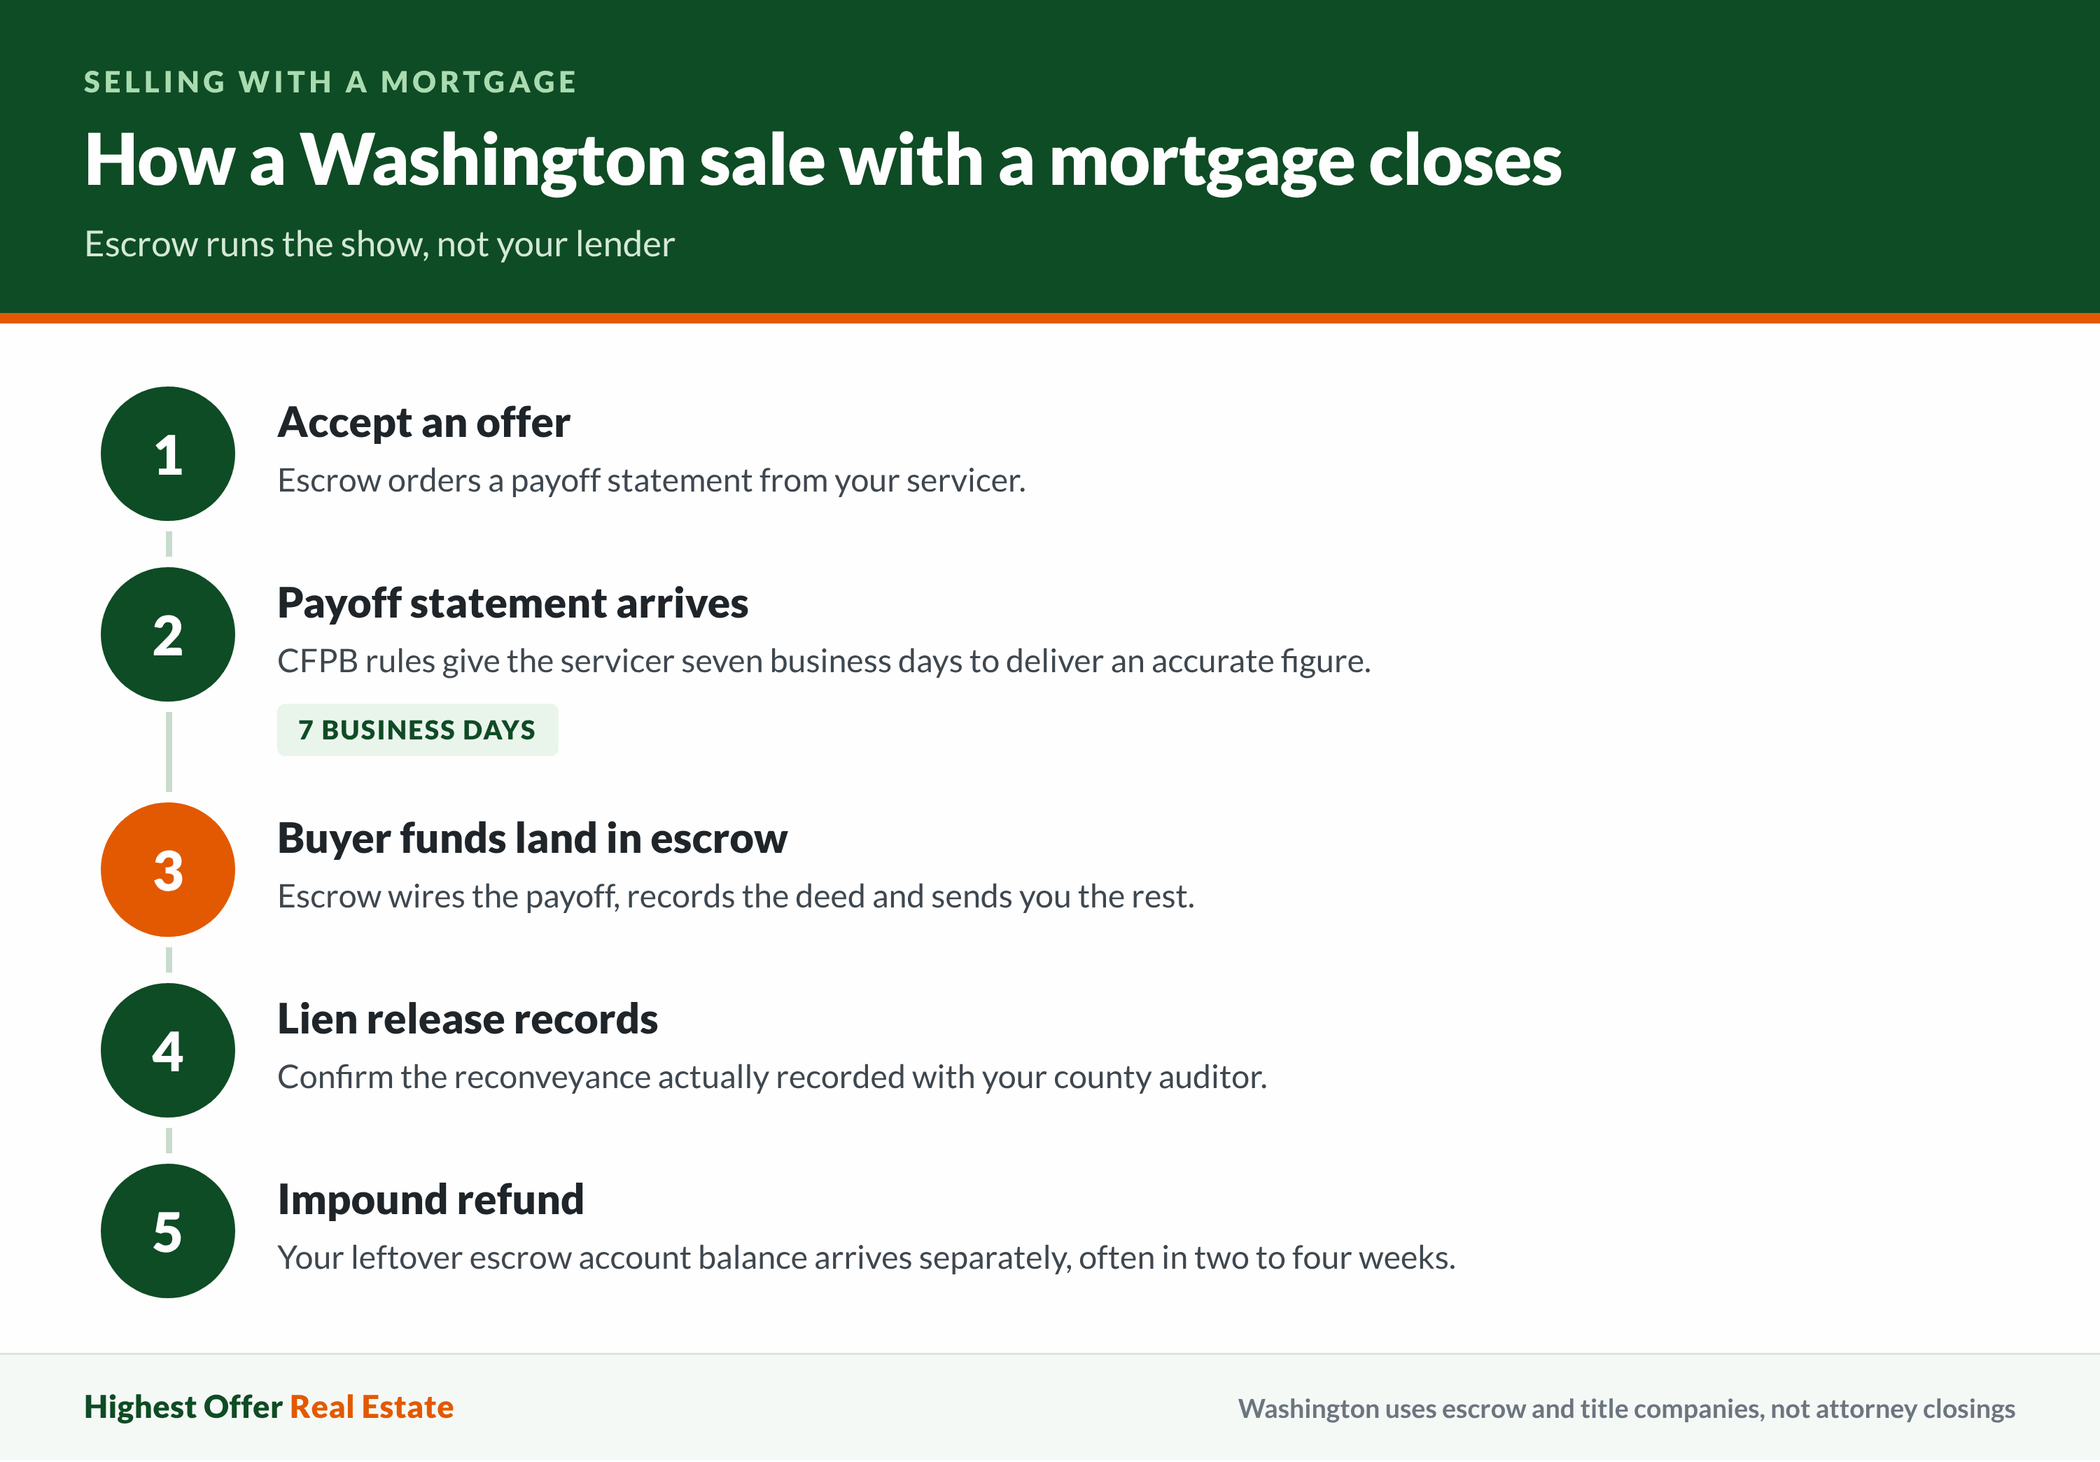
Your lender is the least interesting party in your Washington closing. Escrow runs the show.
Escrow companies and title insurers are used in Washington rather than attorney-led closings, which means the choreography is predictable. Once you accept an offer, escrow orders a payoff statement from your servicer. The document lists remaining principal, interest accrued up to a stated date, and any charges the lender can legally tack on. Under CFPB rules, a servicer must deliver an accurate payoff statement within seven business days of a request, showing the exact amount needed to satisfy the loan as of a specified future date. You can read the agency’s own servicing guidance at consumerfinance.gov.
Buyer funds land in escrow. Escrow wires the payoff to your servicer, records the new deed with the county auditor, and sends whatever’s left to you. The lien release follows.
One Washington wrinkle worth planning for: the state real estate excise tax comes out of your side. The Department of Revenue says the seller normally pays it, and the buyer becomes responsible if the seller doesn’t. Escrow collects it from seller proceeds, then pays the county treasurer when the deed and REET affidavit get recorded. You’ll find current rates posted at dor.wa.gov.
Selling with a mortgage in Washington adds exactly one step to a normal sale: the payoff wire. Everything else looks identical to a cash-free-and-clear transaction.
What Happens to Your Mortgage When You Sell Your Home?
A seller in Puyallup walked into escrow owing just over $300,000. She walked out two hours later owing nothing to that lender, with a wire hitting her account the next business day.
That’s the arc. Your loan doesn’t transfer, follow you, or linger. It gets extinguished.
Here’s where people selling with a mortgage get tripped up: the payoff figure is not your statement balance. The payoff captures remaining principal, interest accrued through a stated good-through date, and any fees the lender is entitled to charge, because interest keeps accruing daily until the wire arrives. A closing that slips four days costs you four more days of interest.
Keep an eye on the good-through date. A payoff quote is typically valid for 10 to 30 days; miss that date and you need a fresh statement reflecting additional accrued interest and possibly updated fees. Washington closings that drag past the quote window stall right there, every time.
After the wire clears, your servicer files a reconveyance releasing the deed of trust. Washington uses deeds of trust with a trustee rather than traditional mortgages in most residential lending, though everyone calls them mortgages anyway. Confirm the release actually recorded with your county auditor. I’ve seen releases sit unfiled for weeks because nobody followed up, and that stray lien surfaces later when you’re trying to buy something else.
Sellers should also care about escrow accounts, but that deserves its own section.
What Happens to Escrow Funds and Second Mortgages When You Sell?
Forget a second lien and your Washington closing dies on the table, because title won’t insure a sale that leaves an unreleased claim on the property.
Remember that HELOC you opened in 2019 to redo the kitchen? It’s a lien. The solar loan filed against your Spanaway house? Also a lien. Every one of them gets paid or formally subordinated before a deed records.
Your impound account is separate money. Taxes and insurance premiums you prepaid belong to you, so the servicer refunds the remaining balance once the loan closes out. Expect that check or deposit somewhere in the two to four week range after payoff, depending on the servicer. It arrives separately from your escrow proceeds, which confuses people who think they got shorted at closing.
Property taxes get prorated through closing day. Washington counties bill twice yearly, and your county treasurer’s office can tell you exactly which installment periods are open on your parcel. Escrow handles the split based on those records.
Second mortgage holders occasionally drag their feet on payoff demands, so give them more runway than you give your first lender. If you’re selling with a mortgage plus a home equity line, request both payoffs the week you go under contract rather than waiting.
One pattern I keep seeing in King and Snohomish County sales: homeowners forget about contractor liens from remodels that ended in a dispute. Those show up in the title report, not in your memory. A preliminary title commitment ordered early gives you time to clear them.
Can You Sell a Home with Negative Equity in Washington?
“If I owe more than it’s worth, I’m stuck.” That’s the objection, and it’s not true.
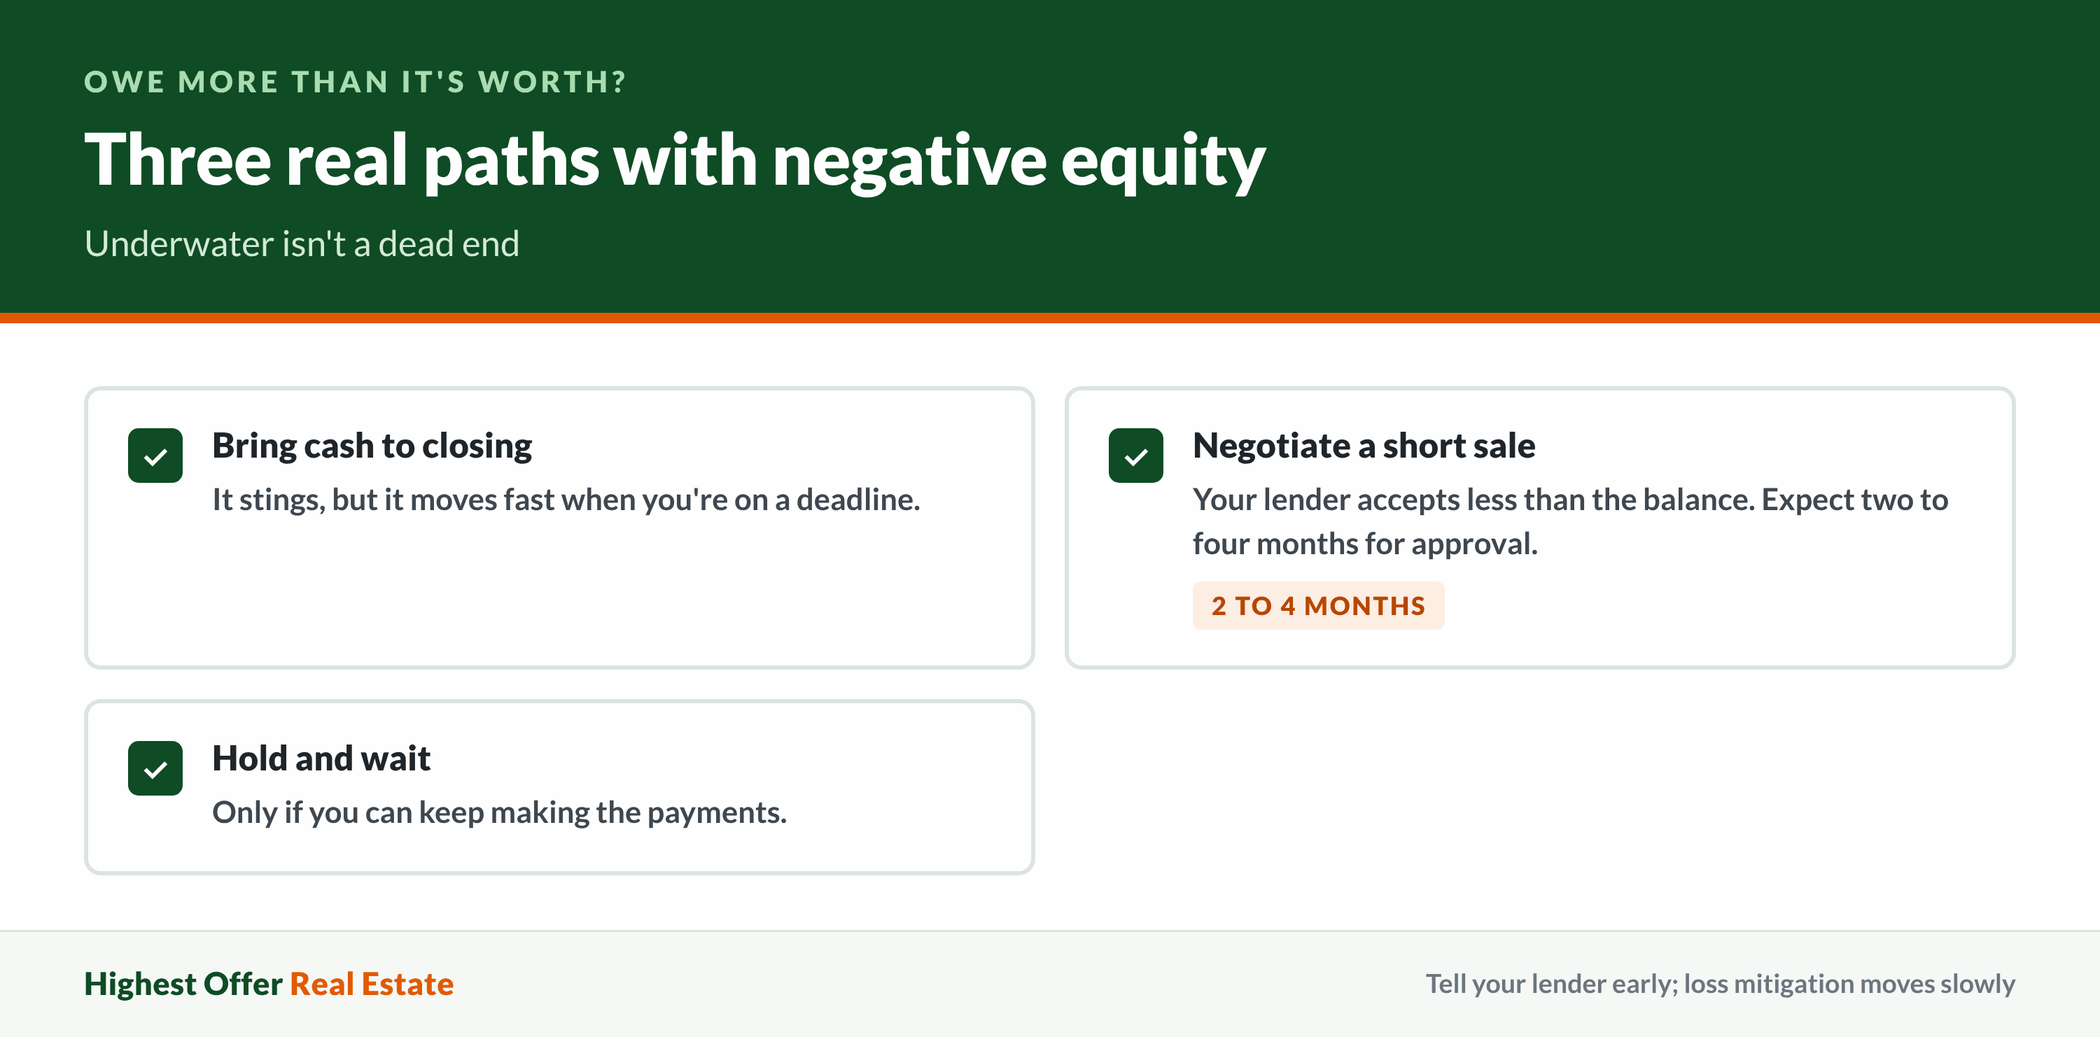
Negative equity in Washington gives you three real paths. You bring cash to closing to cover the gap, or you negotiate a short sale where your lender accepts less than the full balance. Or you hold and wait, assuming you can afford the payments.
Short sales take lender approval and patience from buyers. Washington short sales routinely take two to four months from offer to approval because the servicer orders its own valuation and runs the file through loss mitigation. Any second lienholder has to sign off too, and junior lenders have less incentive to cooperate.
Bringing cash stings but moves fast. For a seller relocating out of Tacoma or Everett on a deadline, writing a check at closing often beats months of short sale limbo.
The math is worth running carefully given current conditions. Pierce County’s median sold price was $566,250 in October 2026, and statewide prices were down 2.4 percent from a year earlier. Modest softening plus a loan taken out at peak pricing is how underwater situations happen, even though the broader Washington market stays healthy.
Should you tell your lender you’re underwater before you list? Yes, and earlier than feels comfortable. Loss mitigation departments move slowly, and a file opened in advance saves weeks later.
Selling with a mortgage you can’t fully cover isn’t a dead end. Direct buyers like Highest Offer Real Estate can often structure around a tight payoff because they’re not waiting on buyer financing or appraisal contingencies.
How Do You Calculate Your Estimated Sale Proceeds?
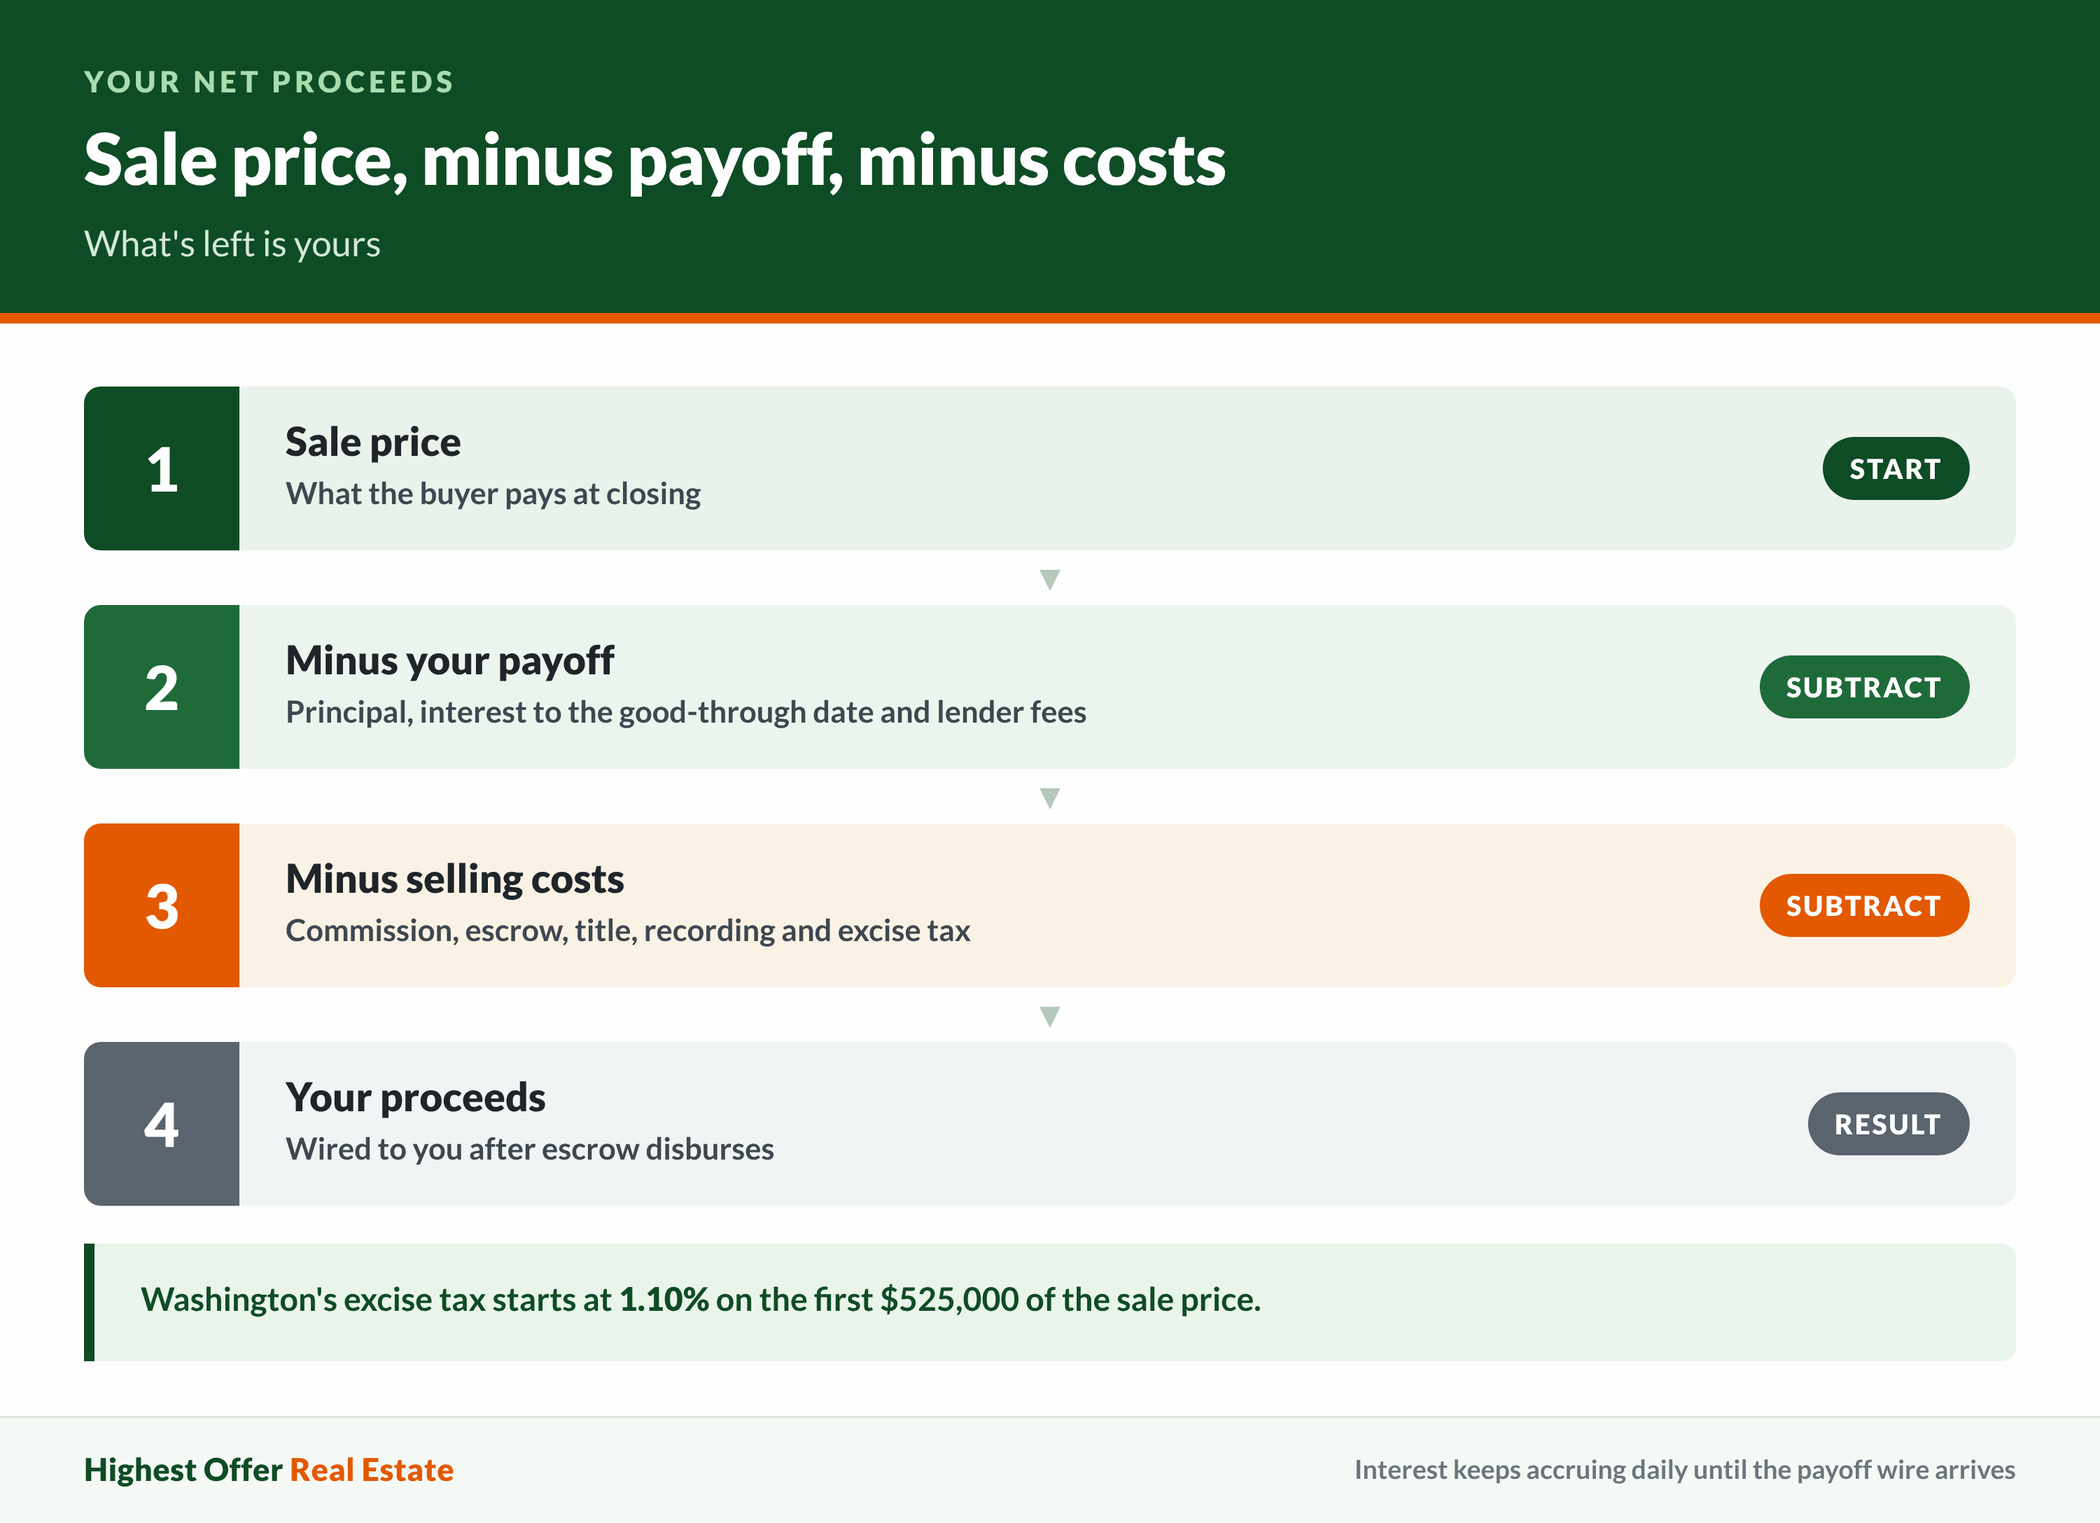
Sit down with a napkin and I’ll show you in three lines. Sale price, minus payoff, minus costs. What’s left is yours.
The costs are where estimates go sideways. Agent commissions remain the biggest chunk in Washington listings, typically landing somewhere around five to six percent of the price depending on what you negotiate with your real estate agent. Escrow fees, owner’s title insurance, and recording charges add up on top.
Then there’s excise tax, which surprises transplants from no-transfer-tax states. Washington’s REET is graduated, starting at 1.10 percent on the first $525,000 of sale price and climbing to 3.00 percent on portions above $3,025,000. A local REET of 0.25 to 0.50 percent is also charged by most cities and counties. The Department of Revenue has already published the next schedule: starting January 1, 2027, the tiers break at $551,000, $1,551,000 and $3,051,000, with the rates unchanged.
Buyer concessions deserve a line in your estimate. In a balanced Washington market, repair credits after inspection are common, and I’d budget for them rather than pretending they won’t come.
Most Washington sellers owe no federal tax on their gain. The IRS allows you to exclude up to $250,000 of gain, or $500,000 on a joint return. This applies if you owned and used the home as your main residence for at least two of the five years before the sale. Full details sit at irs.gov.
Run your numbers twice. The first pass always forgets something, usually prorated taxes or the utility final bills.
What Documents Do You Need to Sell a House with a Mortgage?
For years I told sellers to gather their original loan paperwork, which turns out to be nearly useless at closing.
What escrow actually needs is narrower: your loan number and servicer contact information, government-issued ID, and the recorded deed showing how title is held. It also needs your Washington seller disclosure statement, which state law requires for most residential sales.
Title held in a trust, an LLC, or a deceased spouse’s name adds paperwork. Trustees need the trust certification. Estates need letters testamentary from the Washington superior court in the county where probate was opened.
Divorce decrees and quit claim deeds belong in the pile too, if either applies to your situation. A quit claim removing an ex-spouse from title does not remove them from the loan, and that distinction catches sellers mid-escrow. The debt and the ownership are separate legal threads.
Homeowners association documents matter in planned communities from Issaquah to Lacey. Escrow orders a resale certificate, and HOAs sometimes take two weeks to produce one. Request it the day you go under contract.
Keep every payoff statement and the final settlement statement. Your accountant will want them, and if a servicer ever claims the loan wasn’t satisfied, that paperwork ends the conversation in about ninety seconds. Selling with a mortgage generates a document trail worth preserving for several years.
Can You Qualify for a New Mortgage Before Selling Your House?
A homeowner in Kent wanted to buy a smaller place near her daughter before listing the family home. Her debt-to-income ratio included both payments, and the bank said no.
That’s the usual answer for Washington buyers carrying an existing loan, unless income easily covers both housing payments. Lenders count your current mortgage against you until it’s gone.
Bridge loans solve this for some people selling with a mortgage. They’re expensive and short-term, and they only make sense when the equity cushion is deep. A sale-contingent offer is the free alternative, though in competitive Washington submarkets like Ballard or Kirkland, contingent offers lose to clean ones.
Selling first and renting for a few months is underrated advice. Yes, you move twice. You also negotiate from strength and avoid carrying two payments into a slower season. Seattle’s median house sold for $983,750 as of September 2026, with homes spending a median of 22 days active. That’s quick enough that a short rental gap is manageable.
A different seller, this one in Puyallup, was dividing assets in a divorce and wanted zero involvement in showings. Neither party would agree on a listing price, the garage was full of a boat neither one claimed, and attorneys were billing by the hour. So we bought it as-is on a Thursday with a closing date their mediator picked. Nobody had to stage a single room.
Talking through a timeline with a direct buyer such as Highest Offer Real Estate costs nothing and clarifies whether selling with a mortgage first or buying first fits your situation.
Frequently Asked Questions
Do I Have to Pay Off My Mortgage Before I List My House in Washington?
No, and almost nobody does. Your loan gets satisfied out of the buyer’s funds at closing, handled by the escrow company, so there’s no reason to drain savings beforehand. Washington escrow officers coordinate this payoff daily as part of a routine transaction.
Will My Lender Stop Me From Selling with a Mortgage Still Attached?
Your servicer has no veto power over a sale that pays the loan in full. The only scenario where lender approval genuinely matters is a short sale, where you’re asking them to accept less than what’s owed. In a standard Washington sale, the servicer simply issues the payoff figure and waits for the wire.
How Long Does It Take to Get My Money After Closing in Washington?
Once escrow records the deed with the county auditor and disburses, most sellers see funds by wire within one to two business days. Your leftover impound balance comes separately from the servicer and takes longer. If you’re on a tight timeline, ask your escrow officer to confirm the disbursement date in writing rather than assuming it matches recording day.
What If My Payoff Amount Is Higher Than I Expected?
That gap is usually accrued interest and lender fees rather than an error. Compare the payoff statement against your last billing statement line by line, and ask your servicer to explain anything that doesn’t match. You’re entitled to an accurate figure, and errors do happen with transferred loans.
Can I Sell with a Mortgage If I’m Behind on Payments?
Yes, and selling is often the better outcome than letting the default run its course. Washington uses nonjudicial foreclosure through a trustee, and the timeline moves faster than many homeowners expect once notices start. Getting ahead of it with a sale protects whatever equity you’ve built and keeps a foreclosure off your record.
Does Selling with a Mortgage Change My Tax Situation?
Paying off a loan isn’t a taxable event by itself, since you’re just retiring a debt with sale proceeds. What matters for taxes is your gain, calculated from your purchase price plus improvements against your net sale price. Most Washington homeowners selling a primary residence fall under the federal exclusion described earlier and owe nothing. Still, a CPA is worth an hour of your time if your numbers are close to the limits.
Is Selling with a Mortgage Different for a Rental Property in Washington?
The payoff mechanics are identical, but the tax treatment isn’t. Rental properties don’t qualify for the primary residence exclusion, and depreciation you claimed over the years gets recaptured when you sell. Existing tenants also complicate possession dates, so build that conversation into your timeline before you accept an offer.
If you’re weighing a move and the loan balance is the thing giving you pause, let’s talk it through. I’m happy to look at your numbers and tell you honestly whether listing, selling direct, or waiting makes the most sense for your situation. No pressure, no obligation, and no hard sell if the answer is that you should stay put.
Selling With a Mortgage in Tacoma and Pierce County
Tacoma closings run through the same escrow steps as the rest of the state. Your payoff gets wired at closing, and the lien release records with the Pierce County Auditor.
Order your payoff statement early so the good-through date covers your closing.
Get Your Net Number Before You List
Not sure what you’ll walk away with after the payoff? Contact Highest Offer Real Estate and we’ll run the numbers with you.
You can also fill out the short form below. There’s no cost and no obligation.
Helpful Washington Blog Articles
- How to Sell a House without A Realtor in Washington
- How to Sell a House in Foreclosure in Washington
- Selling a House during Divorce in Washington
- Selling a House With Water Damage in Washington
- Selling Your Washington Home with Code Violations
- Can You Sell a House With Asbestos in Washington
- Who Pays Closing Costs When Selling a House in Washington
- Can You Sell A House With A Lien In Washington
- Selling a House That Needs Repairs in Washington
- Capital Gains Tax on Real Estate in Washington
- How Does Selling a House With a Mortgage Work in Washington
- Selling A House With Solar Panels In Washington
- How To File A Quitclaim Deed In Washington